NHAI reforms lead to steep decline in high-risk highway projects
ROADS & HIGHWAYS

NHAI reforms lead to steep decline in high-risk highway projects

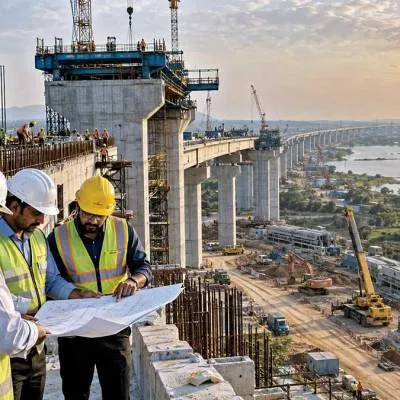
The proportion of under-construction, high-risk highway projects has reduced significantly from 53 per cent two years back to 21 per cent, following a slew of steps initiated by NHAI. These include significantly shorter timelines for right-of-way and approvals, loan support from NHAI for languishing projects, termination of stuck projects and their subsequent re-awarding, and affording a change in sponsor. <p></p> <p>Today, only 2,000 km of the 9,400 km of highway projects under construction awarded by the NHAI on a BOT basis are at high risk. In the operational BOT portfolio, too, approvals for change in sponsor and subsequent refinancing, along with traffic growth, have yielded results. 'About 80 per cent of the operational portfolio comprising nearly 100 BOT projects are at low risk today, in terms of debt servicing,' says <span style="font-weight: bold;">Sachin Gupta, Senior Director, CRISIL Ratings</span>. Apart from reduced risk, policy measures by NHAI have also resulted in doubling of highway construction from 12 km per day in fiscal 2015 to 23 km in fiscal 2017. The pace is expected to quicken to about 40 km per day in the near-term. The awarding of contracts, led by HAM and TOT models, is expected to sustain given the announcement and subsequent implementation of the Bharatmala project. TOT is a new mode of project award initiated by NHAI, and segregates construction and demand risks. However, as a concept, the model is yet to be tested. </p> <p>Operational road assets, especially annuity and HAM projects, will have steady cash flows over the concession period. Even toll projects exposed to traffic and tolling risk yield largely stable cash flows once they are operational. Such projects, with five to 15 years of concession periods, can potentially be refinanced with lower-cost, longer-tenure debt through issue of bonds and non-convertible debentures. <span style="font-weight: bold;">Sushmita Majumdar, Director, CRISIL Ratings, </span>says, 'With stronger sponsors, lower risk and reduced interest costs, CRISIL believes as much as Rs 70,000 crore of debt can be refinanced through bonds or bank loans in the medium term. Additionally, TOT projects could potentially securitise receivables worth ~Rs 40,000 crore, once awarded.</p> <p>In the past two years, Rs 10,000 crore of debt has already been refinanced through the corporate bond market, resulting in an annual interest cost savings of 100-300 basis points for developers.</p>

The proportion of under-construction, high-risk highway projects has reduced significantly from 53 per cent two years back to 21 per cent, following a slew of steps initiated by NHAI. These include significantly shorter timelines for right-of-way and approvals, loan support from NHAI for languishing projects, termination of stuck projects and their subsequent re-awarding, and affording a change in sponsor. <p></p> <p>Today, only 2,000 km of the 9,400 km of highway projects under construction awarded by the NHAI on a BOT basis are at high risk. In the operational BOT portfolio, too, approvals for change in sponsor and subsequent refinancing, along with traffic growth, have yielded results. 'About 80 per cent of the operational portfolio comprising nearly 100 BOT projects are at low risk today, in terms of debt servicing,' says <span style="font-weight: bold;">Sachin Gupta, Senior Director, CRISIL Ratings</span>. Apart from reduced risk, policy measures by NHAI have also resulted in doubling of highway construction from 12 km per day in fiscal 2015 to 23 km in fiscal 2017. The pace is expected to quicken to about 40 km per day in the near-term. The awarding of contracts, led by HAM and TOT models, is expected to sustain given the announcement and subsequent implementation of the Bharatmala project. TOT is a new mode of project award initiated by NHAI, and segregates construction and demand risks. However, as a concept, the model is yet to be tested. </p> <p>Operational road assets, especially annuity and HAM projects, will have steady cash flows over the concession period. Even toll projects exposed to traffic and tolling risk yield largely stable cash flows once they are operational. Such projects, with five to 15 years of concession periods, can potentially be refinanced with lower-cost, longer-tenure debt through issue of bonds and non-convertible debentures. <span style="font-weight: bold;">Sushmita Majumdar, Director, CRISIL Ratings, </span>says, 'With stronger sponsors, lower risk and reduced interest costs, CRISIL believes as much as Rs 70,000 crore of debt can be refinanced through bonds or bank loans in the medium term. Additionally, TOT projects could potentially securitise receivables worth ~Rs 40,000 crore, once awarded.</p> <p>In the past two years, Rs 10,000 crore of debt has already been refinanced through the corporate bond market, resulting in an annual interest cost savings of 100-300 basis points for developers.</p>

Related Stories

Gold Stories
Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code