- Home
- Infrastructure Urban
- ECONOMY & POLICY
- Why India’s GDP is leaking!
Why India’s GDP is leaking!
The KV Kamath panel, set up to recommend eligibility parameters for the restructuring of loans for specific sectors hit by Covid-19, identified 26 sectors. It said power, construction, iron and steel, roads, real estate, wholesale trading, textiles, consumer durables, aviation, logistics, hotels, restaurants and tourism and mining are among the sectors that would require restructuring. This will further add to the drain in resources this year. The only way to plug this leak is by privatisation of banks. In an earlier article, “Are we headed for a Hindu rate of growth?”, I had cited the case of the wealth HDFC Bank has built for its shareholders and, therefore, the case for privatisation of banks. The RBI panel has recently recommended that the corporate sector be allowed to set up private banks. Raghuram Rajan and Viral Acharya have vehemently argued against this. I concur. However, NBFCs such as those set up by Bajaj, L&T, Mahindra & Mahindra and Aditya Birla Group could qualify as their presence in the financial services sector could meet the needs of net worth, track record and reputation.
Increasing the number of banks could be another way to build value but it does not stop the leak in our GDP bucket. Last year, we completed 50 years of bank nationalisation and over the past six years, even the current NDA Government has witnessed the decimation of wealth under its watch. Prime Minister Narendra Modi has already sought a reduction in the government stake from four banks: Punjab & Sind, UCO Bank, Bank of Maharashtra and IDBI Bank (LIC now owns 51% of it). But the pace of privatisation and divestment has been too lackadaisical.
India’s disinvestment target for 2020-21 is Rs 2.1 trillion against last year’s achievement of Rs 34.85 billion, against the 2019-20 target of Rs 1.05 trillion. Divestment crossed Rs 1 trillion only in 2017-18 in the past 10 years—Rs 37 billion from this was received by selling shares internally among PSUs; ONGC bought the Government’s 51% stake for cash. The second highest divestment was in 2018-19 of Rs 80 billion. So, while FY 2018 and FY 2019 did send out a good signal for divestment, FY 2020 has slipped. A recent respite has come in the form of the BPCL disinvestment, which will provide succour in the form of Rs 400 billion and is not an eyewash as PSUs have been expressly forbidden from participating in the divestment process. The second most profitable PSU has elicited no response from Reliance, TOTAL, Aramco or BP, signalling that the family silver is corroding in value over time.
Other than BPCL, there are 19 more PSUs for which the Government has given in-principle approval for disinvestment, including the likes of Container Corporation of India, Bharat Earth Movers and Shipping Corporation of India. Given the tepid response to BPCL, this leak does not look like it will be plugged anytime soon.
The other hole is power distribution. Politicians have forced state electricity boards or discoms to sell electricity free or at highly subsidised rates to farmers and their vote banks. Discoms have, by now, accumulated losses of nearly Rs 1 trillion and have huge arrears of payment to suppliers like Coal India and the Railways. Here, too, privatisation of discoms is the answer.
Restoration of GDP will need these leaks to be plugged.
Author: Pratap Padode is Editor-in-Chief, Construction World, & Founder, FIRST Construction Council.
Also read: Utility segments remain bright spots
- BPCL
- RBI
- PM Modi
- Reliance
- Container Corporation of India
- Shipping Corporation of India
- Pratap Padode
- economy
- NPA basket
- Union Budget 2019
- COVID-19
- KV Kamath panel
- Raghuram Rajan and Viral Acharya
- NBFCs
- GDP bucket,Punjab & Sind
- UCO Bank
- Bank of Maharashtra and IDBI Bank ,LIC
- Prime Minister Narendra Modi
- ONGC
- discoms
- Coal India
- Railways
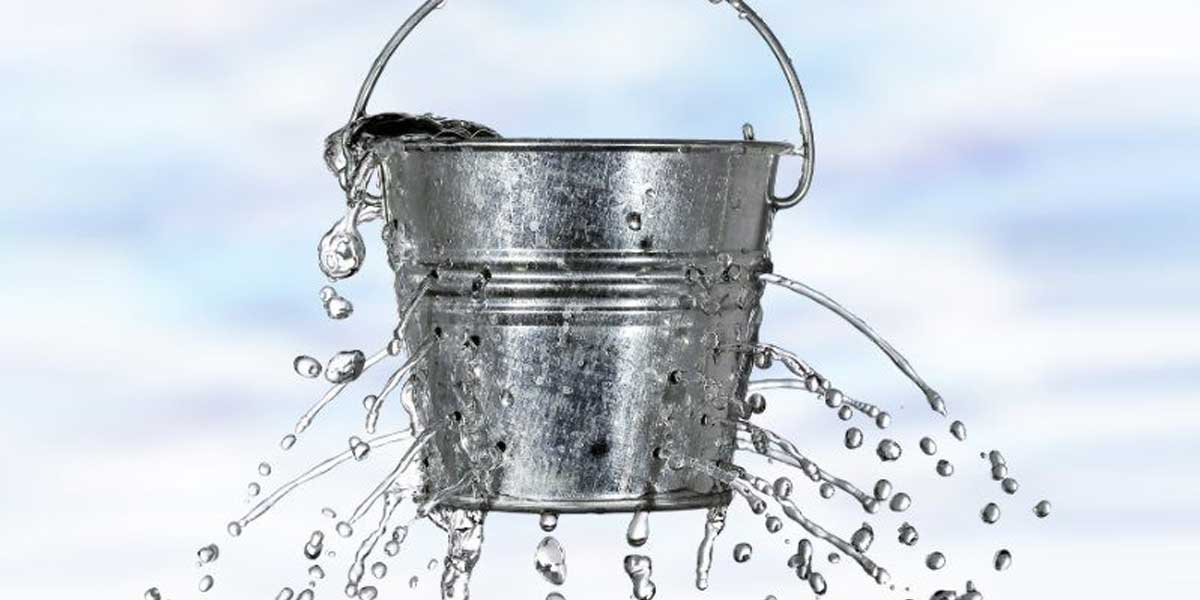
India has a leaking bucket. So even while the economy grows, it is unable to benefit from the growth as our resources so added are not deployed efficiently. Even though our second quarter results indicate that the economy shrank by 7.5% as we unlocked our cities, our recoveries are stymied by the leakage in the system. One of the holes in its bucket is created by the banking sector. Between FY09 and FY19, the Government infused Rs 3.15 trillion in public sector banks. The Union Budget 2019 further provided for a Rs 700 billion provision to recapitalise banks. As on 30 September 2019, the public-sector banks were carrying non- performing assets (NPAs) of Rs 7.27 trillion. While moratorium and loan restructuring will cause a pause in the ever-increasing numbers in the NPA basket, there will a fresh round of recapitalisation very soon. Every year, the taxpayers fund Rs 2 trillion of NPAs of banks according to some estimates. RBI data shows that Indian banks wrote off nearly $85 billion over FY14-FY19, of which state-owned banks contributed nearly 80%. The KV Kamath panel, set up to recommend eligibility parameters for the restructuring of loans for specific sectors hit by Covid-19, identified 26 sectors. It said power, construction, iron and steel, roads, real estate, wholesale trading, textiles, consumer durables, aviation, logistics, hotels, restaurants and tourism and mining are among the sectors that would require restructuring. This will further add to the drain in resources this year. The only way to plug this leak is by privatisation of banks. In an earlier article, “Are we headed for a Hindu rate of growth?”, I had cited the case of the wealth HDFC Bank has built for its shareholders and, therefore, the case for privatisation of banks. The RBI panel has recently recommended that the corporate sector be allowed to set up private banks. Raghuram Rajan and Viral Acharya have vehemently argued against this. I concur. However, NBFCs such as those set up by Bajaj, L&T, Mahindra & Mahindra and Aditya Birla Group could qualify as their presence in the financial services sector could meet the needs of net worth, track record and reputation. Increasing the number of banks could be another way to build value but it does not stop the leak in our GDP bucket. Last year, we completed 50 years of bank nationalisation and over the past six years, even the current NDA Government has witnessed the decimation of wealth under its watch. Prime Minister Narendra Modi has already sought a reduction in the government stake from four banks: Punjab & Sind, UCO Bank, Bank of Maharashtra and IDBI Bank (LIC now owns 51% of it). But the pace of privatisation and divestment has been too lackadaisical. India’s disinvestment target for 2020-21 is Rs 2.1 trillion against last year’s achievement of Rs 34.85 billion, against the 2019-20 target of Rs 1.05 trillion. Divestment crossed Rs 1 trillion only in 2017-18 in the past 10 years—Rs 37 billion from this was received by selling shares internally among PSUs; ONGC bought the Government’s 51% stake for cash. The second highest divestment was in 2018-19 of Rs 80 billion. So, while FY 2018 and FY 2019 did send out a good signal for divestment, FY 2020 has slipped. A recent respite has come in the form of the BPCL disinvestment, which will provide succour in the form of Rs 400 billion and is not an eyewash as PSUs have been expressly forbidden from participating in the divestment process. The second most profitable PSU has elicited no response from Reliance, TOTAL, Aramco or BP, signalling that the family silver is corroding in value over time. Other than BPCL, there are 19 more PSUs for which the Government has given in-principle approval for disinvestment, including the likes of Container Corporation of India, Bharat Earth Movers and Shipping Corporation of India. Given the tepid response to BPCL, this leak does not look like it will be plugged anytime soon. The other hole is power distribution. Politicians have forced state electricity boards or discoms to sell electricity free or at highly subsidised rates to farmers and their vote banks. Discoms have, by now, accumulated losses of nearly Rs 1 trillion and have huge arrears of payment to suppliers like Coal India and the Railways. Here, too, privatisation of discoms is the answer. Restoration of GDP will need these leaks to be plugged.Author: Pratap Padode is Editor-in-Chief, Construction World, & Founder, FIRST Construction Council. Also read: Utility segments remain bright spots
Related Stories
Gold Stories
Peninsula Land launches 19 luxury villas in Pune
Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
MyBranch Expands South India Network with 16 Workspace Centres
MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Walplast Launches Moisture-Resistant Gypsum Plaster Solutions
Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..
Related Articles
Latest Updates
Recommended for you
Advertisement
Subscribe to Our Newsletter
Get daily newsletters around different themes from Construction world.
subscribe to the newsletter
Don't miss out on valuable insights and opportunities
to connect with like minded professionals